Reporting Global Income: How Indonesia Enforces Taxation on Worldwide Assets
One of the most heart-stopping moments for any expat is receiving a formal notification from the Indonesian tax office (DJP) asking about "unreported assets" held in their home country. I remember the cold sweat I broke into when I first realized my modest savings back home weren't as invisible as I had hoped. This guide breaks down exactly how Indonesia tracks and taxes your global income.
Understanding the Tax Residency Trap
The first hurdle every foreigner faces is determining whether they are actually a tax resident. In Indonesia, the line between being a "tourist with a laptop" and a "Resident Taxpayer" (Wajib Pajak Dalam Negeri) is thinner than you might think. Generally, if you spend more than 183 days in the country within any 12-month period, or if you reside here with the "intention to stay"—which is almost always signaled by holding a KITAS or KITAP—you are considered a tax resident.
Once you cross that threshold, the Indonesian government technically expects you to report and pay tax on your worldwide income. This doesn't just mean the salary you earn from a local PT PMA; it includes the rental income from your flat in London, the dividends from your portfolio on Interactive Brokers, and even the interest sitting in a high-yield savings account in Sydney. Navigating Tax Residency Rules: The 183-Day Test and "Intention to Stay" Definitions is essential because the moment you are classified as a resident, your global financial life becomes an open book to the Directorate General of Taxes (DJP).
I’ve seen many expats try to argue that because their money never enters an Indonesian bank account, it doesn't count. Unfortunately, that logic doesn't hold up under the current "World Wide Income" principle. The Indonesian tax system is designed to capture wealth wherever it is generated, provided the individual generating it calls Indonesia home for more than half the year. This is why understanding Taxes in Indonesia for Expats: NPWP, PPh 21, and the 183-Day Rule is the first step toward staying out of legal trouble.
How the DJP Actually Enforces Global Reporting
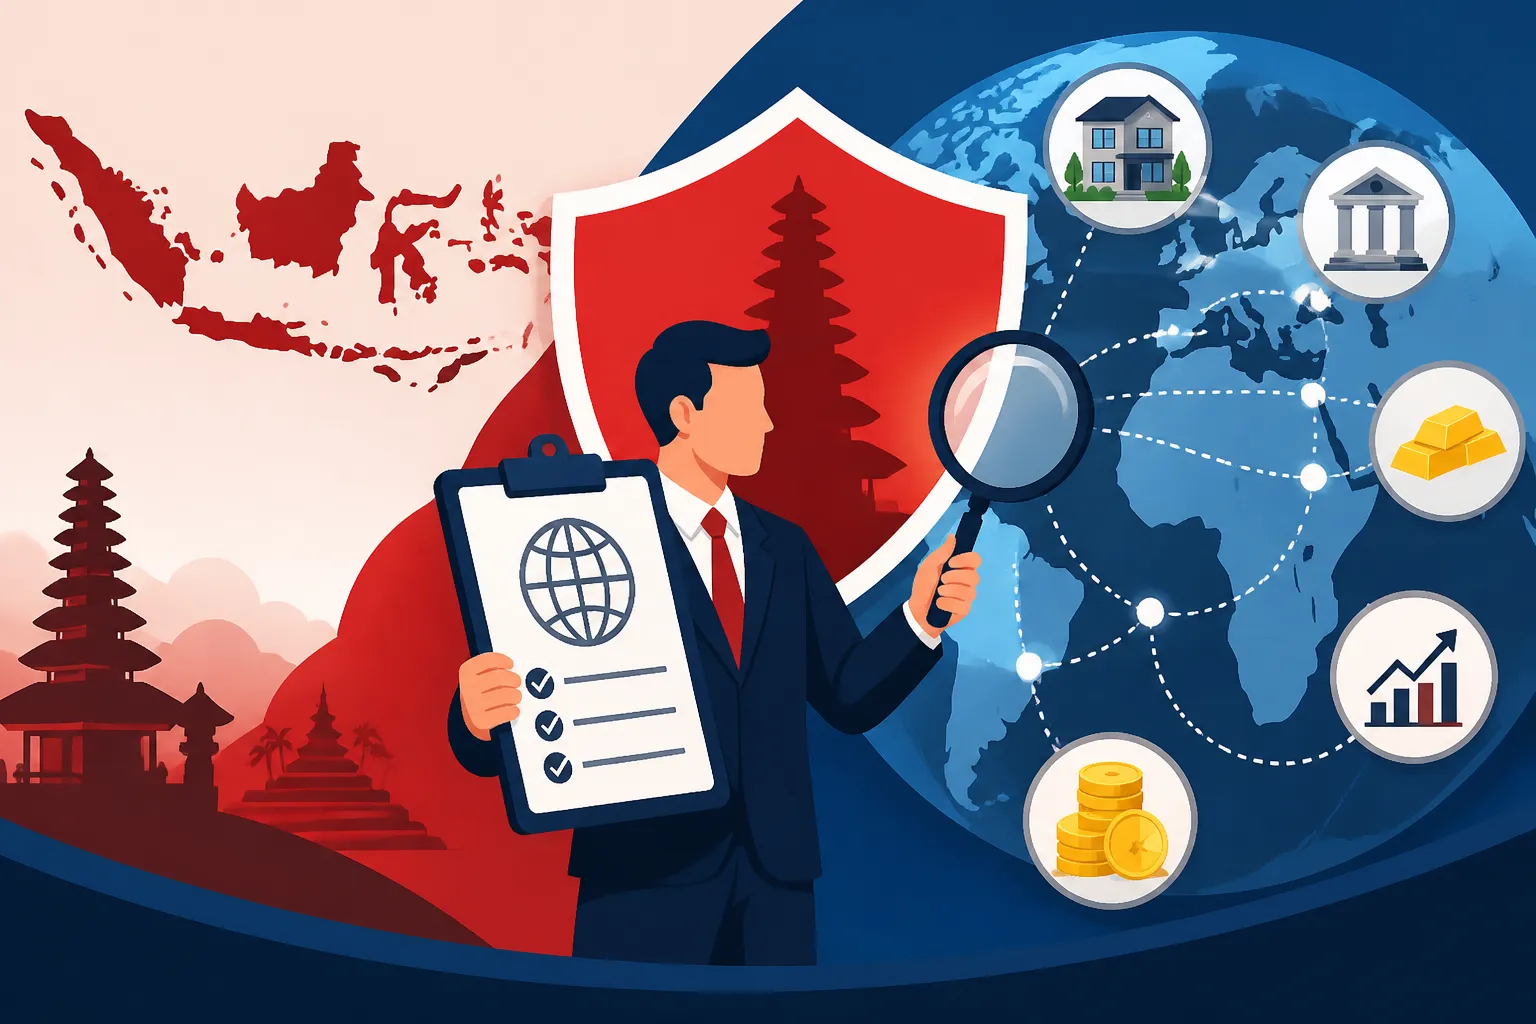
You might be wondering, "How would they even know about my account in Switzerland?" A decade ago, they probably wouldn't have. Today, however, Indonesia is an active participant in the Automatic Exchange of Information (AEOI) and the Common Reporting Standard (CRS). This means that over 100 countries automatically share financial account information with the Indonesian tax authorities. If your home bank has your Indonesian address or NPWP on file, that data is likely being pinged back to Jakarta.
Furthermore, the integration of the NIK (National Identity Number) with the NPWP (Tax ID) has made the system far more efficient. When you go through the process of Registering for an NPWP (Tax ID): How Expats Link NIK to Tax Records in 2027, you are essentially centralizing your identity. The tax office uses sophisticated data-matching algorithms to flag discrepancies between your lifestyle in Bali or Jakarta and the income you declare on your annual return. If you're buying property or luxury cars locally but reporting a minimum wage salary, the red flags go up immediately.
For those of us managing international investments, the digital trail is becoming harder to obscure. Even if you are trading on platforms like Binance, the Indonesian government has implemented specific VAT and income tax rules for crypto-assets. They are looking at everything. I always recommend using a secure connection via NordVPN when accessing your overseas financial portals to ensure your data remains private from third-party prying eyes, but remember that the "privacy" a VPN provides does not exempt you from the legal requirement to report those accounts to the DJP.
The 4-Year Foreign Expert Exemption
There is a silver lining for certain professionals, and it’s one of the most underutilized benefits in the Indonesian tax code. If you qualify as a "Foreign Expert" with specific skills that are not readily available in the local labor market, you may be eligible for a territorial tax basis for your first four years of residency. This means you would only be taxed on income earned within Indonesia, leaving your global assets untouched for that period.
To qualify, your job title and expertise must align with specific government regulations. This is a massive relief for those moving here with significant passive income streams back home. You can find the specific requirements in our guide on The 4-Year Tax Exemption on Worldwide Income: Eligibility for Foreign Experts. If you don't fit into this specific category, you fall back into the standard pool where every dollar, euro, or yen earned globally is subject to the progressive tax brackets, which can climb as high as 35%.
In my experience, many expats assume they automatically get this exemption just because they are "foreigners." That is a dangerous assumption. You must actively ensure your work permit and tax registration reflect this status. If you miss this window or fail to document your expertise correctly, you could end up owing back taxes on a decade's worth of global dividends.
Navigating Double Tax Agreements and Remittances
The biggest fear for most of us is being taxed twice—once in the country where the money was earned and again in Indonesia. Thankfully, Indonesia has signed Double Tax Agreements (DTA) with over 70 countries. These treaties are designed to ensure you aren't unfairly burdened. Typically, you can claim a "Foreign Tax Credit" (PPh Pasal 24) in Indonesia for taxes already paid abroad.
However, the paperwork is a nightmare. You often need to provide a Certificate of Domicile or Form DGT to your home country's tax authority to prove you are a resident of Indonesia. When it comes to actually moving your money, using a service like Wise is the gold standard for expats. It’s not just about the lower fees; it’s about having a clear, transparent record of "clean" money transfers that have already been accounted for in your tax filings. I’ve found that having a clean paper trail via International Money Transfers: Using Wise, SWIFT, and Local Bank Remittances makes the annual audit much less stressful.
| Income Type | Reporting Requirement | Potential Tax Treatment |
|---|---|---|
| Foreign Salary | Mandatory | Progressive rates (5% to 35%) |
| Foreign Dividends | Mandatory | Subject to DTA credits |
| Global Rental Income | Mandatory | Reported in SPT 1770 |
| Crypto Gains | Mandatory | Specific local rates may apply |
| Offshore Interest | Mandatory | Often triggers AEOI flags |
Filing the Annual Return and Managing Audits
In Indonesia, the tax year runs from January to December, and individual filings are due by March 31st of the following year. This is the moment of truth where you must fill out the "Lampiran" (attachments) listing your global assets. This includes bank balances, property, and even jewelry or expensive electronics. It feels invasive, but the goal is "Net Wealth Tracking"—the DJP wants to see that your increase in wealth year-over-year matches your declared (and taxed) income.
If you find yourself in the crosshairs of an audit, don't panic, but don't ignore it either. The DJP has the power to issue "SP2DK" (request for explanation) letters. If your numbers don't add up, you might need professional help. Knowing the process for Filing the Annual Tax Return (Formulir 1770): Deadlines and Required Documents is vital, but so is knowing when to call in the pros. I’ve lived through an audit where I had to explain why I moved a large sum of money from my Interactive Brokers account to buy a villa lease; having the records ready saved me thousands in potential fines.
For many, the best path is Hiring a Local Tax Consultant (Konsultan Pajak): Fees and Finding English Speakers. A good consultant will help you navigate the e-Filing portal and ensure you aren't overpaying. They can also represent you if you need to learn How to Dispute an Incorrect Tax Assessment by the Directorate General of Taxes. Remember, the Indonesian tax office is surprisingly open to discussion if you approach them with transparency, but they are unforgiving if they feel you are intentionally hiding assets.
Summary of Key Expat Financial Tips
Managing your money in Indonesia is about more than just finding a good exchange rate. It requires a fundamental shift in how you view your global financial footprint. The days of "offshore" being "out of sight" are over.
- Audit your residency: If you're on a KITAS, you're likely a tax resident. Act accordingly.
- Keep records: Save every tax receipt from your home country to claim your credits.
- Be transparent: It is almost always cheaper to declare and pay a small amount than to get caught in an AEOI sweep.
- Secure your digital life: Use NordVPN for financial logins, but keep your reporting honest.
- Plan your exit: Before you leave the country, ensure you have a "Tax Clearance" to avoid issues with your EPO (Exit Permit Only).
Living in this beautiful archipelago is a dream, but the administrative reality requires diligence. By staying informed through resources like Money in Indonesia for Foreign Residents: Banking, Tax, and Financial Setup (2027), you can enjoy your life in the sun without the shadow of the taxman hanging over your shoulder.
Disclaimer
This article is for informational purposes only and does not constitute professional tax, legal, or financial advice. Indonesian tax laws are subject to frequent change and individual interpretation by tax officers. Always consult with a certified Indonesian tax consultant (Konsultan Pajak) or legal professional before making financial decisions or filing your tax returns in Indonesia.