What Does BPJS Health Actually Cover? Free Treatments vs Exclusions
One of the most confusing moments for any newcomer is seeing that first mandatory deduction for BPJS Kesehatan on a payslip. When I first moved to Jakarta, I genuinely wondered if this was just another "expat tax" or a system that would actually catch me if I fell. This guide breaks down exactly what those monthly contributions buy you and where the "free" service ends.
The Gotong Royong Philosophy: More Than Just Insurance
Before we dive into the line items of what is covered, you have to understand the spirit of the system. BPJS Kesehatan isn't a private insurance product designed for profit; it is based on the Indonesian concept of gotong royong, or mutual cooperation. Essentially, the healthy pay for the sick. For us as foreign residents, it is a mandatory part of the BPJS Kesehatan for Expats: Registration, Costs, and the New KRIS System requirements if you are working or staying long-term on a KITAS.
In the early days of my residency, I viewed it with a lot of skepticism. I was used to private, high-premium international plans. However, after seeing friends navigate significant surgeries with almost zero out-of-pocket costs, my perspective shifted. It is a massive, bureaucratic safety net. It won't give you a private suite with a view of the city skyline, but it will ensure you aren't bankrupt after an appendectomy. To manage the administrative side of things, many expats use a NordVPN to securely access their banking and the Mobile JKN app when traveling or using public Wi-Fi, ensuring their personal health data remains private.
What is Actually Free: The Core Coverage Areas
The range of "free" treatments under BPJS is surprisingly broad, covering everything from the common flu to chronic life-threatening conditions. As long as you follow the procedure, the following services are generally covered 100% without a copay.
Outpatient Primary Care
Your journey always starts at your "Faskes 1" (First-Level Healthcare Facility). This is usually a local Puskesmas (community health center) or a private clinic that has partnered with BPJS. This covers:
- General practitioner consultations.
- Basic laboratory tests (blood work, urine analysis).
- Standard medications listed in the National Formulary.
- Emergency dental care (extractions and basic fillings).
If you are used to the Public vs Private Healthcare in Indonesia: BPJS Kesehatan and Expat Insurance debate, you’ll find that while Faskes 1 can be crowded, the medical standard is regulated. I’ve found that choosing a private clinic as your Faskes 1 rather than a public Puskesmas can lead to a slightly more "expat-friendly" experience with shorter wait times.
Inpatient Hospitalization and Surgery
This is where the value of BPJS really shines. If your primary doctor refers you to a hospital, or if you are admitted via the ER for a true emergency, BPJS covers:
- The hospital room (now transitioning to the KRIS system).
- Surgical procedures, including major surgeries like heart bypass or oncology treatments.
- ICU, NICU, and recovery room stays.
- Nursing care and diagnostic imaging (X-rays, CT scans, MRIs).
The shift to Transitioning to KRIS: What Standard Inpatient Classes Mean for Expats means that the old "Class 1, 2, and 3" system is being replaced by a more uniform standard. While this simplifies the bureaucracy, it also means you may no longer have the option to "pay the difference" easily for a VIP room within the BPJS track.
Chronic Disease Management
If you suffer from hypertension or diabetes, the system provides ongoing support. The Prolanis program is designed to manage these chronic conditions through regular check-ups and monthly medication supplies. Navigating the Apotek Guide: Prescription Workflow, Refills, and Communicating with Pharmacists is vital here, as you must collect your medication from specific BPJS-partnered pharmacies.
The Referral System: The Golden Ticket to Care
The biggest "catch" with BPJS is that you cannot simply walk into a top-tier hospital like Siloam or RSPI and expect it to be free. The system is strictly tiered. Unless it is a life-threatening emergency, you must get a digital referral from your Faskes 1.
In my experience, this is the part that frustrates foreigners the most. You might know you need to see a cardiologist, but you still have to visit your local GP first to get that referral. If you try to skip this step, you will be treated as a "general" (private) patient and billed accordingly. This is a common topic in the Jakarta Healthcare Guide for Expats: International Clinics and After-Hours Options because the extra steps can feel tedious when you are feeling unwell.
When paying your monthly premiums to keep your status active, using a service like Wise is often the most cost-effective way to move funds from your home country into your local Indonesian bank account, such as Mandiri or BCA, which then auto-debits your BPJS fees. Keeping your account funded is crucial; if you miss a payment, your "free" coverage is suspended immediately.
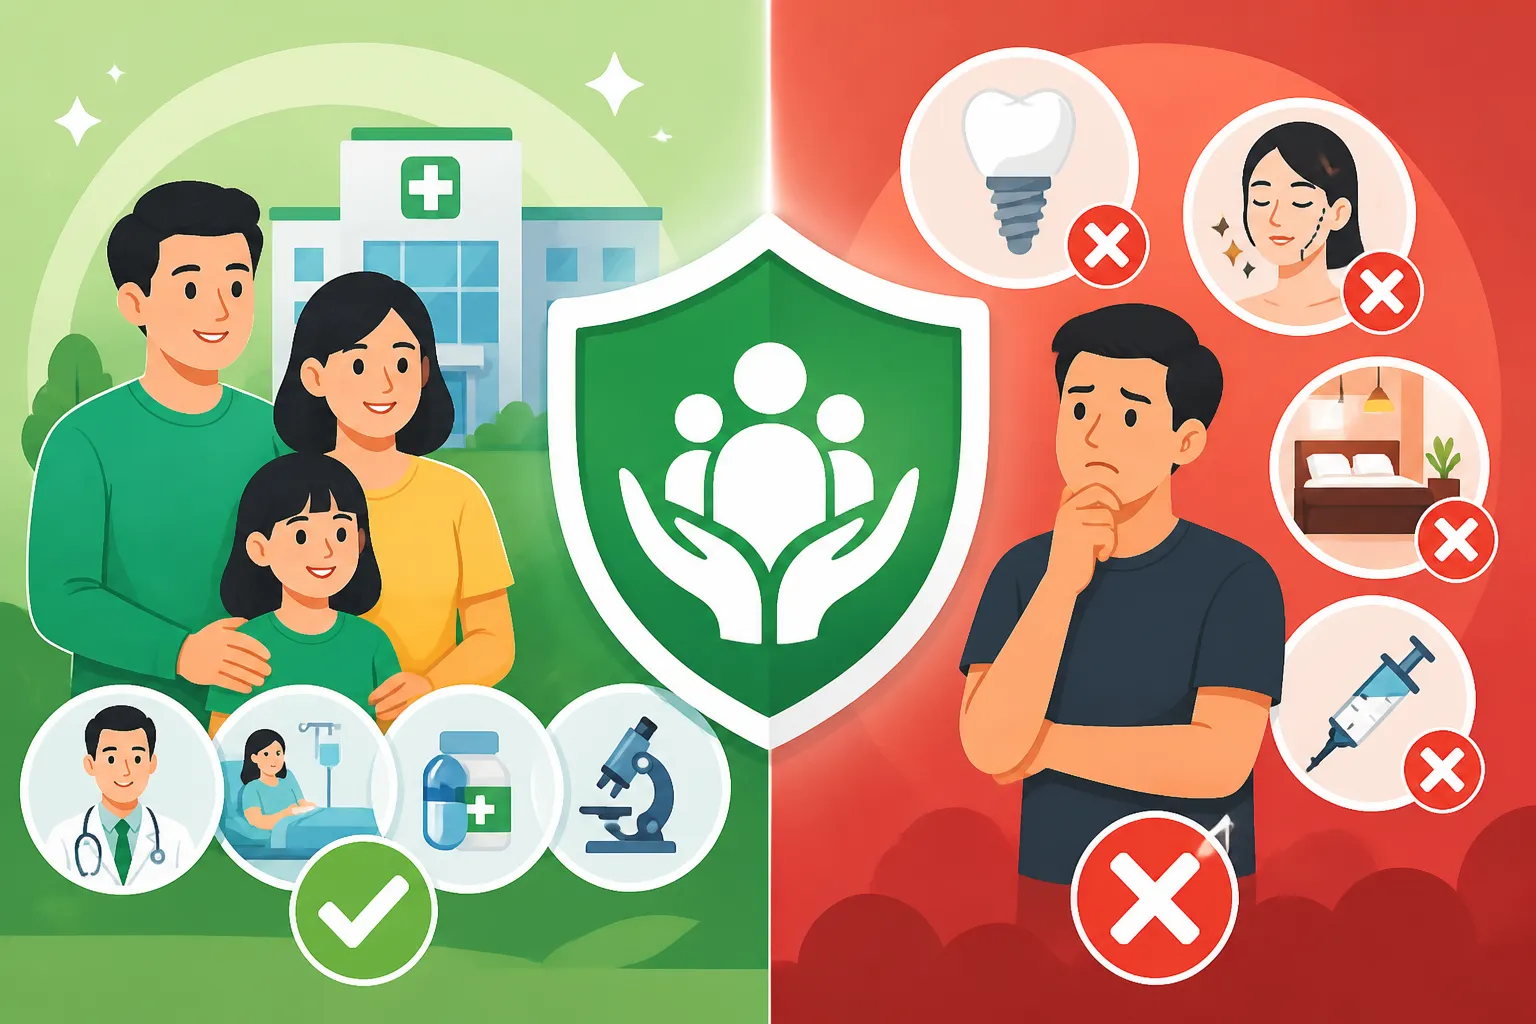
| Category | Covered by BPJS Kesehatan | Common Exclusions / Out-of-Pocket |
|---|---|---|
| Consultations | GP and Specialists (with referral) | Direct specialist visits without referral |
| Medication | Generic drugs in the National Formulary | Brand-name drugs or imported vitamins |
| Emergency | ER stabilization and admission | Non-emergency ER visits (triaged as low priority) |
| Hospital Stay | Standard KRIS Wards | VIP or VVIP Private Suites |
| Dental | Extractions, scaling (once a year), basic fillings | Braces, whitening, implants, and bridges |
| Optical | Basic lenses and subsidized frames | High-index lenses, designer frames, LASIK |
| Maternity | Natural birth and C-sections (if medically necessary) | Elective C-sections and luxury birthing suites |
Major Exclusions: What You Will Have to Pay For
While the list of covered items is long, the exclusions are very specific. If you go into a medical situation expecting BPJS to cover everything, you might be in for a shock when the final bill arrives.
Cosmetic and Aesthetic Procedures
Anything deemed non-medical is strictly excluded. This includes plastic surgery for aesthetic reasons, hair transplants, or skin treatments for acne that aren't part of a larger pathology. If you are looking for these services, you are better off consulting the Bali Healthcare Guide: Hospitals, Clinics, and Emergency Contacts for Residents to find high-end private aesthetic clinics that cater to expats.
Infertility and Birth Control Restrictions
While basic family planning (like the pill or IUDs) is often covered at the Faskes 1 level, advanced fertility treatments like IVF are not covered. Furthermore, while maternity care is comprehensive, it is designed for medical necessity. If you want a specific "luxury" birthing experience with a private midwife and a water birth, these are typically considered out-of-pocket expenses. You can find more details in our guide on Pregnancy and Childbirth in Indonesia: Prenatal Care, Birth Options, and Hospitals.
Overseas Medical Care
BPJS is strictly a domestic system. It provides zero coverage if you decide to fly to Singapore for a second opinion or a specialized surgery. For many residents, this is the primary reason to maintain a secondary private insurance policy. In cases of extreme illness, the costs of Medical Tourism in Southeast Asia: Flying to Singapore or Malaysia for Care can be astronomical without a private international plan.
Self-Inflicted Injuries and Substance Abuse
Treatment for injuries resulting from attempted suicide, or medical issues arising from drug or alcohol addiction, often falls into a gray area or is explicitly excluded from the social security net. Similarly, injuries sustained from "hazardous" activities without proper licensing (like riding a motorbike in Bali without a valid SIM C) can sometimes lead to complications in claim approvals if the police report indicates illegal activity.
Bridging the Gap: Why Expats Use Private Insurance
Most veterans I know use BPJS as their "catastrophic" backup while relying on private insurance for day-to-day comfort. The reality of the Public vs Private Healthcare in Indonesia: BPJS Kesehatan and Expat Insurance landscape is that BPJS can be slow. If you need a non-urgent MRI, you might wait weeks under BPJS, whereas private insurance gets you in the same afternoon.
Furthermore, many expats maintain investment portfolios through Interactive Brokers or hold assets in Binance to ensure they have a "health-specific" liquid fund. Having 100 million IDR sitting in a high-yield local account can be the difference between waiting for a BPJS referral and just paying for a private specialist out of pocket when you’re in pain.
Using your BPJS card (Kartu JKN) effectively requires patience and a bit of "system-savviness." For example, knowing Using Your BPJS Card (Kartu JKN): How to Register and Book at Local Faskes through the mobile app can save you hours of sitting in a physical waiting room just to get a queue number.
Practical Steps to Maximize Your Coverage
If you are going to pay for it, you might as well use it. To ensure you get the "free" treatment you are entitled to, follow these steps:
- Download the Mobile JKN App: This is non-negotiable. It shows your digital card, your registered clinic, and allows you to book appointments.
- Verify Your Faskes 1: Make sure the clinic assigned to you is actually near your house. If you live in Kemang but your KITAS was processed with an address in North Jakarta, your Faskes might be two hours away. You can change this once every three months via the app.
- Keep Your NPWP Linked: The government is increasingly linking Taxes in Indonesia for Expats: NPWP, PPh 21, and the 183-Day Rule with social services. Ensure your tax ID and residency papers are up to date to avoid administrative freezes.
- Always Carry Your KTP-WNA: When you go to a hospital under BPJS, they will ask for your card and your KTP WNA (Foreigner ID Card): Why Banks Will Ask You For It. Having these ready speeds up the triage process significantly.
Handling Emergencies: When the Rules Change
In a true emergency—think a heart attack or a serious accident—the referral rule is waived. You can go to the nearest ER (UGD) of any hospital that accepts BPJS. They are legally required to stabilize you. However, once you are stable, if that hospital does not have an agreement with BPJS, they may ask to transfer you to a partner facility or start charging you private rates. Understanding the Emergency Medical Care in Indonesia: Ambulances, ERs, and Evacuation Protocols is vital for these high-stress moments.
I always tell new arrivals: treat BPJS as your base layer. It is the generic, reliable foundation that ensures you won't be turned away from a hospital in a crisis. But for the "expat lifestyle" of English-speaking doctors, private rooms, and zero wait times, you will still want to keep your private options open.
Important Medical Disclaimer
The information provided in this guide is for informational purposes only and does not constitute professional medical or legal advice. Healthcare regulations in Indonesia, particularly those involving BPJS Kesehatan and the KRIS system transition, are subject to frequent change by the Ministry of Health and BPJS authorities. Always verify current coverage details with your employer's HR department, your local BPJS office, or the official Mobile JKN application. Neither the author nor this publication assumes liability for medical decisions made or expenses incurred based on this content. For medical emergencies in Indonesia, please dial 118 or 119 immediately.