Insuring Your Rented Villa: Fire, Earthquake, and Liability Coverage
Most expats moving to Bali or Jakarta assume that because they’ve paid a massive sum of rent upfront, the landlord has everything under control regarding property protection. I remember sitting in my first Seminyak villa, listening to the walls creak during a minor tremor, and realizing I had absolutely no idea whose responsibility it was if the roof caved in. This guide clarifies the confusing world of villa insurance to ensure you aren't left bankrupt by a "force majeure" event.
Why Your Landlord's Insurance Isn't Enough
The first thing you need to understand about Renting in Indonesia: The 1-Year Upfront Rule, Contracts, and Avoiding Scams is that the legal burden often shifts to the tenant in ways that feel alien to Westerners. In many countries, the building owner carries a comprehensive policy that protects the structure and anyone inside it. In Indonesia, while a landlord might have a basic policy required by their bank, it almost never covers the tenant's personal belongings, nor does it provide you with liability protection if a guest drowns in your pool or a fire starts in your kitchen and spreads to the neighbor’s property.
When you sign those Understanding Indonesian Lease Agreements: Notarized Contracts and Stamp Duty, look closely at the "force majeure" and "maintenance" clauses. Most Indonesian leases state that the landlord is responsible for major structural issues, but they are remarkably silent on what happens if your laptop, camera gear, and designer furniture are destroyed by a ceiling leak or a fire. I have seen expats lose twenty thousand dollars worth of electronics in a single afternoon because of a power surge from a faulty PLN transformer, only to find their landlord simply shrug and point to the contract.
To manage these risks, you need your own tenant-specific insurance policy. Paying for these premiums is becoming easier, and using a service like Wise allows you to transfer the necessary Rupiah from your home currency without getting destroyed by the "hidden" exchange rate fees that local Indonesian banks often tack on. Having a clear financial trail of your insurance payments is also vital if you ever need to prove your expenses for Taxes in Indonesia for Expats: NPWP, PPh 21, and the 183-Day Rule or during a legal dispute.
Protecting Against the Arus Pendek: Fire and Lightning Coverage
In Indonesia, the phrase "Arus Pendek" (short circuit) is something you will hear constantly. It is the leading cause of house fires in both the crowded neighborhoods of Jakarta and the tropical villas of Bali. Many villas are built quickly, and the salt air in coastal areas can corrode wiring faster than you’d believe. If a fire breaks out, the local fire department (Damkar) may struggle to reach your villa due to narrow gang (alleys) or heavy traffic.
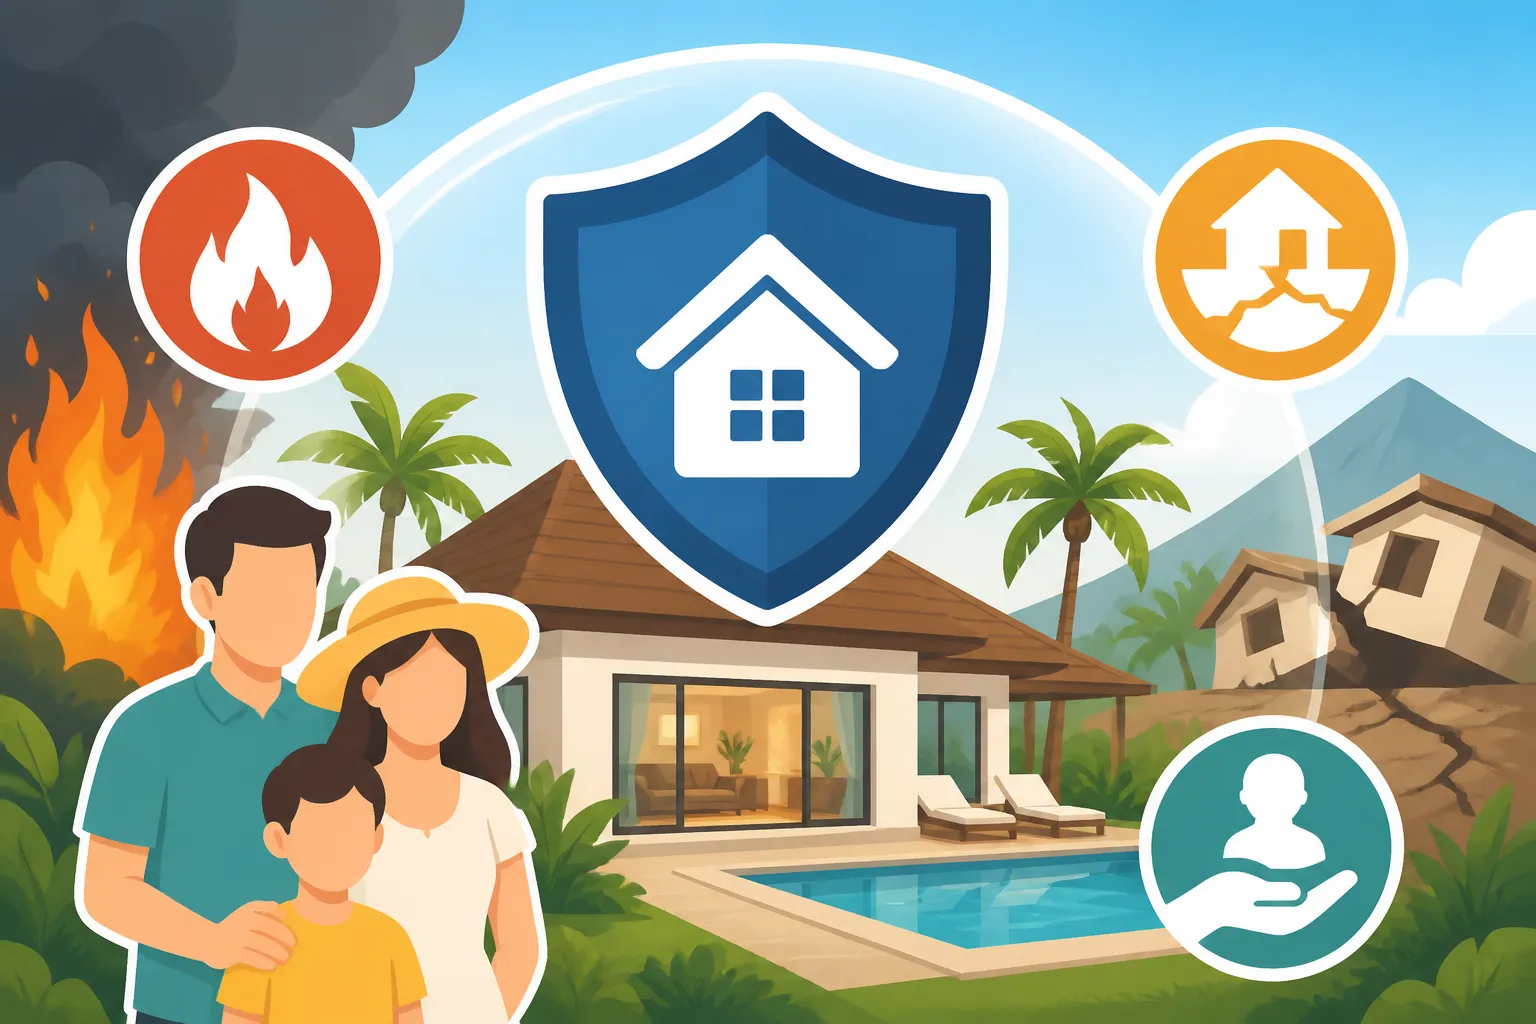
Standard fire insurance in Indonesia usually falls under a "Property All Risks" (PAR) or a "Flexas" policy. Flexas covers Fire, Lightning, Explosion, Aircraft Impact, and Smoke. As a renter, you aren't necessarily insuring the "bricks and mortar" for the landlord, but you are insuring the "First Loss" or the contents and the liability. If a fire starts because you left a candle burning or an overloaded power strip failed, the landlord’s insurance company might actually come after you to recoup their losses.
This is where "Tenant’s Liability to Landlord" coverage becomes your best friend. It ensures that if you accidentally burn the villa down, the insurance company pays the landlord, not your personal savings account. When setting up these policies or researching providers, I always suggest using NordVPN to ensure your connection is encrypted, especially if you are accessing sensitive financial documents or insurance portals from a public co-working space in Canggu.
Earthquakes and Volcanic Risks: Living on the Ring of Fire
Indonesia is one of the most seismically active countries on earth. While we all love the aesthetic of open-plan living and heavy tiled roofs, these structures can be vulnerable during a significant tremor. Most standard fire policies in Indonesia exclude earthquake, volcanic eruption, and tsunami damage by default. You have to add a specific "Earthquake Extension" which is governed by the Indonesian Earthquake Insurance Maipark.
The cost of this extension depends on the zone your villa is in. Bali and parts of Java are in higher-risk zones than, say, Kalimantan. When you live here long-term, you start to realize that Earthquake Preparedness: Alerts (BMKG App) and Evacuation Plans are not just suggestions; they are part of the lifestyle. An earthquake policy won't just cover the cracks in the wall; a good policy for a tenant will cover "Alternative Accommodation." If your villa becomes uninhabitable due to a quake, the policy pays for you to stay in a hotel while repairs are made.
Without this, you might find yourself still tied to a lease for a villa you can't live in, while also paying for a hotel out of pocket. This can be a massive drain on your Everyday Budgeting in Indonesia: Cost of Living in Jakarta vs Bali vs Regional. Protecting your liquidity is key, whether that's through insurance or by keeping your broader investment portfolio accessible via platforms like Interactive Brokers so you aren't forced to liquidate assets at a loss just to cover an emergency move.
Public Liability: The Often Overlooked Essential
If you are renting a villa with a pool, public liability insurance is not optional—it is a necessity. If a guest, a delivery driver, or even a member of your household staff is injured on your property, you could be held liable for their medical expenses and loss of income. In Indonesia, these situations are often handled through "musyawarah" (communal consensus), which can involve significant "peace-making" payments to the local community or the injured party's family.
A robust Public Liability (or Third-Party Liability) policy provides a legal buffer. It covers:
- Accidental bodily injury to third parties.
- Accidental damage to third-party property.
- Legal defense costs if a claim goes to court.
I have known expats who had to pay for a neighbor’s roof after a tree on their rented property fell during a storm. The landlord claimed it was "maintenance" (your responsibility), and the neighbor wanted the money immediately. If you have insurance, you can hand that headache over to an adjuster. As you navigate these risks, it's wise to keep your Financial Checklist for Your First 30 Days in Indonesia updated to include a review of your liability limits every time you renew your lease.
Comparison of Common Villa Insurance Coverage in Indonesia
| Coverage Type | What it Covers | Is it Usually Standard? | Expat Priority Level |
|---|---|---|---|
| Flexas (Fire) | Fire, Lightning, Explosion, Smoke | Yes | Critical |
| Earthquake | Quakes, Tsunami, Volcanic Eruption | No (Requires Extension) | High |
| Flood | Water damage from heavy rain/overflow | No (Requires Extension) | Medium (Location dependent) |
| Theft/Burglary | Loss of items following forced entry | Usually | High |
| Public Liability | Injury to guests or damage to neighbors | Often Optional | Critical (especially with pools) |
| Alternative Accommodation | Hotel costs if villa is uninhabitable | Optional | Medium |
Navigating Exclusions and The "Small Print"
One of the biggest frustrations with Indonesian insurance is the list of exclusions. For example, many policies will not cover theft unless there is "visible evidence of forced entry." If you leave your front door unlocked or your villa staff leaves a gate open and someone walks in and takes your laptop, the insurance company will likely deny the claim. This is why understanding Who Pays for Repairs? Typical Maintenance Responsibilities in Leases and Safety 101: Petty Theft, ATM Skimming, and Home Security in Indonesia is so important—insurance is your last line of defense, not your first.
Another common exclusion is "Gross Negligence." If the insurance company determines that you haven't maintained the AC units and one catches fire, they might try to argue that the fire was preventable. Always keep your receipts for AC servicing and electrical checks. If you are managing multiple properties or have a high-net-worth lifestyle here, you might even be tracking your crypto assets on Binance to stay ahead of inflation; just remember that while digital assets are portable, your physical liability in a villa is very much rooted in Indonesian law.
Finally, be aware of the "Deductible" or "Self-Retention." For earthquake claims, the deductible is often quite high—sometimes 2.5% of the total sum insured. This means for a small crack, it might not be worth claiming, but for a major disaster, it's the only thing standing between you and a total loss of your lease investment.
How to Apply for Villa Insurance as a Tenant
Getting insured isn't as bureaucratic as getting a KITAS, but it does require some paperwork. You will typically need to provide:
- A copy of your Lease Agreement.
- A copy of your Passport and KITAS (though some companies accept a Tourist Visa with a higher premium).
- A "Schedule of Contents"—a list of your expensive items (laptops, cameras, art) with their replacement values.
- Photos of the villa from all four sides and photos of the fire extinguishers (which you should definitely buy if the villa doesn't have them).
Once you have your policy, keep a digital copy in a secure cloud drive. I’ve seen people lose their physical policy documents in the very fires or floods they were trying to insure against. Being prepared isn't about being paranoid; it's about acknowledging that in a beautiful, tropical, and sometimes unpredictable environment like Indonesia, a little bit of foresight goes a long way in protecting your "Pulau Dewata" dream.
Disclaimer on Insurance and Financial Advice
This guide is for informational purposes only and is based on personal expat experiences and general market conditions in Indonesia. Insurance laws and policy wording can change frequently. You should always consult with a licensed insurance broker or legal professional in Indonesia before signing any policy or lease agreement. We do not guarantee the approval of any insurance claim or the reliability of specific providers mentioned.