Private Health Insurance in Indonesia: Bridging the Gap When BPJS Isn’t Enough
You are standing in a humid hospital corridor in South Jakarta, clutching a referral paper that looks like a 1980s receipt, only to be told the specialist is out for lunch indefinitely. I have been there, sweating through my shirt while trying to navigate the bureaucratic maze of the public system. This guide explains how to use private insurance to bridge those frustrating gaps and secure the medical care you actually need.
Understanding the BPJS Framework and Its Real-World Constraints
When you first arrive in Indonesia, you will likely hear about the mandatory national health insurance, BPJS Kesehatan. While it is a commendable social safety net that provides millions with access to care, it is often a culture shock for those used to Western private healthcare standards. The system is built on a tiered referral model, meaning you cannot simply walk into a top-tier hospital because your knee hurts. You must first visit your designated primary clinic (Faskes Tingkat 1), which is often a modest neighborhood facility with limited English-speaking staff.
The referral process is the first major hurdle. I remember waiting for nearly four hours at a local clinic just to get a stamp of approval to see a cardiologist at a larger hospital. Even then, the cardiologist might only have a ten-minute window for you because they are seeing fifty patients in a single afternoon. This high-volume environment can lead to a feeling of being processed rather than being cared for. For those with a KITAS, BPJS Kesehatan for Expats: Registration, Costs, and the New KRIS System is mandatory, but it is rarely sufficient as a standalone solution for those who value time and comfort.
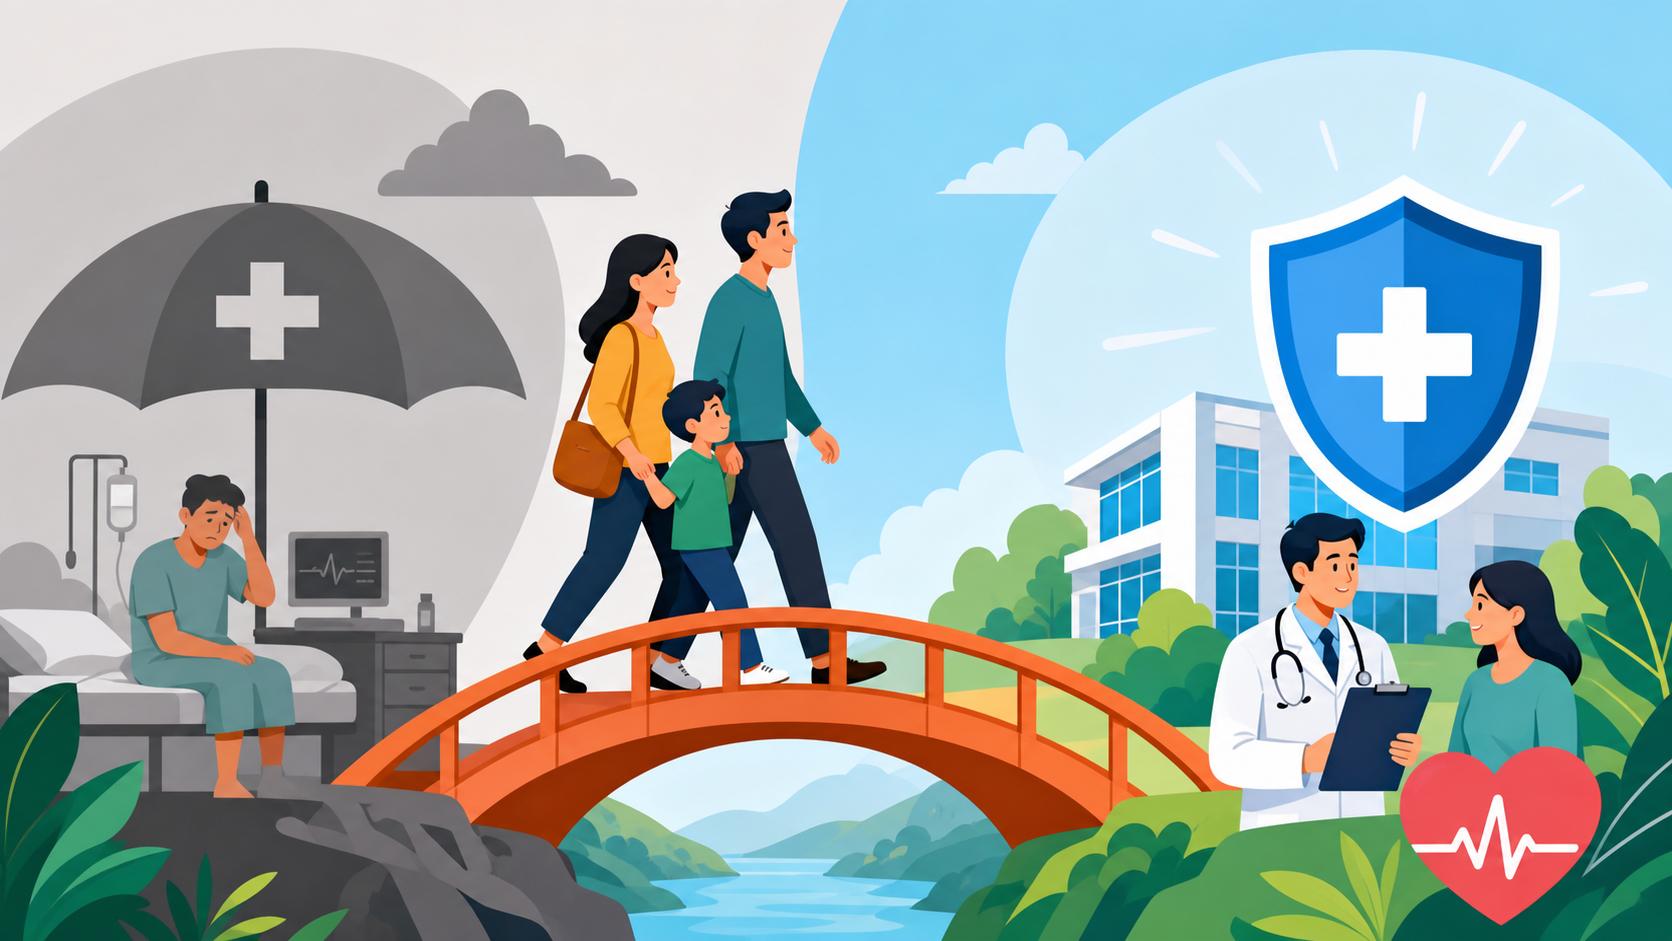
Another critical shift in the landscape is the transition to the KRIS (Kelas Rawat Inap Standar) system. Previously, BPJS offered Class 1, 2, and 3 wards, with Class 1 being the most private. However, the government is moving toward a standardized ward system. For an expat, this means the dream of a private room via BPJS is effectively over. You will likely be in a shared room with several other patients, which can be challenging for recovery if you value privacy or have a family that wants to stay by your side. This is where private insurance becomes a "bridge" to a private suite or a VIP room.
Why Private Health Insurance is a Vital Safety Net
The primary reason most of us in the expat community opt for private coverage is speed. In a private facility like Siloam or Medistra, the "red tape" is replaced with a concierge-style experience. You can book appointments via an app like Halodoc or directly through the hospital's WhatsApp line, often securing a slot the same day. This efficiency is not just about luxury; it is about preventing a minor ailment from spiraling into a major complication while you wait for a referral.
Choice of facility is the second major pillar. Indonesia has some world-class private hospitals, particularly in Jakarta and Bali. If you are covered by a reputable international provider, you have direct access to Siloam Hospitals Overview: What Expats Should Know About the Network. These facilities are equipped with the latest diagnostic technology—think high-resolution MRIs and robotic surgery suites—that might not be available or accessible in the public tier. In Bali, having a policy that covers BIMC Hospital Bali: Services, Costs, and Insurance Direct Billing Options is almost a prerequisite for peace of mind, especially given the costs associated with tourist-heavy medical hubs.
Direct billing is the "gold standard" of private insurance features. Nothing is more stressful than being asked to pay 50 million Rupiah upfront via credit card before a surgeon will even scrub in for an appendectomy. High-quality private plans, such as those offered by Cigna Global, typically have direct billing arrangements with major hospital groups. You simply show your digital or physical insurance card, and the hospital coordinates the payment with the insurer. This removes the massive burden of the reimbursement process, which in Indonesia can involve a mountain of notarized paperwork and long delays.
Comparing Local vs International Private Insurance
When looking at private options, you will generally choose between a local Indonesian policy and an International Private Medical Insurance (IPMI) plan. Local policies, often provided by companies like Prudential Indonesia or Allianz, are generally more affordable and are tailored to the local market. They are excellent for "topping up" your BPJS coverage, allowing you to upgrade your hospital room class or access a wider network of local specialists without breaking the bank.
However, local plans often have lower "inner limits." This means they might cover your surgery but only up to a certain amount for the surgeon’s fee or a specific cap on the daily room rate. If you choose a high-end hospital like RS Pondok Indah, a local plan might leave you with a significant "excess" or out-of-pocket cost. This is why many veteran expats prefer the comprehensive nature of Public vs Private Healthcare in Indonesia: BPJS Kesehatan and Expat Insurance comparisons, looking for plans that offer a "full refund" for major inpatient procedures.
International plans, like Cigna Global, are designed for the nomadic or highly mobile expat. The biggest advantage here is portability. If you decide to spend a summer in Europe or find yourself needing specialized treatment in Singapore, an international plan travels with you. Furthermore, these plans tend to have much higher annual limits—often in the millions of dollars—which is crucial if you face a catastrophic illness. They also provide access to a global network of medical experts for second opinions, which can be life-saving if a local diagnosis seems uncertain.
Essential Features to Look for in a Policy
Before you sign on the dotted line, you need to scrutinize the "exclusions" and "riders." One often overlooked feature is medical evacuation, or Medevac. Indonesia’s geography is challenging; if you are surfing in Sumba or trekking in Kalimantan and have a serious accident, the local clinics will not be enough. You need coverage that will fly you in a pressurized medical jet to Jakarta or even Singapore. Understanding the nuances of Medical Evacuation (Medevac) Services in Indonesia: Costs and Insurance Coverage is critical for anyone living outside the main Java-Bali hubs.
Outpatient coverage is another area where policies vary wildly. Some expats choose "Inpatient Only" plans to keep premiums low, intending to pay for GP visits and basic medications out of pocket. This can be a smart move, but remember that diagnostic tests like blood work and scans can add up quickly. If you have children, you might want a plan that covers routine vaccinations and pediatric checkups. While you can find basic medicines at a local Apotek Guide: Prescription Workflow, Refills, and Communicating with Pharmacists, specialized medications can be expensive and are often better managed through a robust outpatient rider.
Pre-existing conditions are the bane of the insurance world. Most local Indonesian insurers will apply a "waiting period" (often 12 to 24 months) for conditions you already had before joining. Some international plans offer "Medical Underwriting" where they might agree to cover a pre-existing condition for an additional premium, or they might exclude it entirely. It is vital to be 100% honest during the application. I have seen claims rejected because an expat failed to mention a minor back injury from ten years ago that suddenly flared up into a herniated disc requiring surgery.
Practical Strategies for Layering BPJS and Private Insurance
The most successful residents in Indonesia use a hybrid approach. They maintain their mandatory BPJS for chronic, long-term conditions and minor issues that can wait. For example, if you need routine blood sugar monitoring for diabetes, BPJS is incredibly cost-effective. You can get your monthly checkups and basic insulin at almost no cost. For daily health maintenance, many expats also use iHerb to source high-quality vitamins and supplements that are either unavailable locally or heavily taxed at retail stores.
However, for anything "acute" or life-altering, they switch to their private insurance. If you suspect you have contracted a tropical illness, you don't want to wait in a public queue. Referencing a guide on Tropical Disease Prevention: Vaccines, Treatments, and Local Realities can help you identify symptoms, but a private clinic will get you the lab results in hours rather than days. This layering ensures that you are never at the mercy of a single system’s failure.
Managing the "co-pay" or "excess" is the final part of the strategy. If you have a private plan with a $500 deductible, you might use BPJS for the initial consultations and only "activate" your private insurance for the actual surgery. Just be aware that moving a patient from a BPJS track to a private track within the same hospital can sometimes be an administrative headache. It is often smoother to start in the private wing if you know the condition is serious. Always keep a digital folder of your records, as Hospital Billing in Indonesia: Avoiding Overcharges and Understanding Inpatient Fees becomes much easier to navigate when you have a clear paper trail of every test and consultation.
Cost Analysis and Budgeting for Expat Healthcare
Budgeting for healthcare in Indonesia requires a two-pronged approach: the fixed monthly premiums and the variable out-of-pocket costs. While BPJS is a small percentage of your salary (capped at a relatively low amount), private premiums will depend on your age, lifestyle, and the level of coverage. A healthy 30-year-old might find a local private plan for as little as $60 a month, whereas a comprehensive international plan for a family of four could easily exceed $800 a month.
| Insurance Type | Average Monthly Cost (USD) | Best For | Key Limitation |
|---|---|---|---|
| BPJS Kesehatan | $10 – $12 (Class 1) | Chronic care, legal compliance | Long wait times, shared wards |
| Local Private (Top-up) | $50 – $150 | Hospital room upgrades, local specialists | Inner limits on specific procedures |
| International (IPMI) | $150 – $500+ | Global portability, Medevac, VIP care | High premiums for older residents |
| Out-of-Pocket (No Insurance) | Variable | Minor GP visits, basic labs | Financial ruin in case of major accidents |
Don't forget the "hidden" costs of healthcare. Even with the best insurance, you will likely spend money on items the policy doesn't cover. This includes specialized dental work, high-end maternity care beyond the "standard" delivery package, and imported supplements from iHerb for specific dietary needs. It is wise to keep an emergency "medical fund" of at least $2,000 in a local bank account, even if you have premium insurance. This ensures that in the absolute worst-case scenario—such as a billing dispute or a communication breakdown between the hospital and the insurer—you can pay the deposit and focus on getting better.
Navigating Healthcare in Indonesia for Foreign Residents: Complete System Overview (2027) is a marathon, not a sprint. By securing a private policy that complements your BPJS, you are not just buying a piece of paper; you are buying the right to a faster, more comfortable, and potentially life-saving medical experience in your new home.
Disclaimer
The information provided in this guide is for informational purposes only and does not constitute professional medical or financial advice. Healthcare regulations and insurance policies in Indonesia are subject to frequent change. Always consult with a licensed insurance broker or a legal professional before purchasing a policy, and seek immediate help from qualified medical professionals in the event of a health emergency.